Introduction
Investors often compare an investment’s return with a market index. However, return alone does not explain how much market risk was taken to achieve the result. A portfolio may outperform because of effective decisions—or simply because it was more sensitive to market movements. Jensen’s Alpha helps put that performance into context.
Jensen’s Alpha is a risk-adjusted measure used to estimate whether a security, mutual fund or portfolio earned more or less than the return predicted by the Capital Asset Pricing Model (CAPM). It considers the portfolio’s actual return, risk-free rate, beta and market return.
What Is Jensen’s Alpha?
Jensen’s Alpha measures the difference between an investment’s actual return and the return it was expected to earn for its level of systematic, or market-related, risk.
The measure is named after economist Michael C. Jensen and is generally expressed as a percentage. In simple terms, it answers one question:
Did the investment generate a return above or below what CAPM predicted for the market risk taken?
Suppose a portfolio earned 14% in a year. That may appear strong, but it needs context. If CAPM suggests the portfolio should have earned 11% given its beta and market conditions, its Jensen’s Alpha is +3%. If its expected return was 16%, its alpha is −2% despite the positive actual return.
Understanding CAPM and Beta
Jensen’s Alpha is based on CAPM. The model estimates an asset’s expected return by considering the risk-free rate and its sensitivity to the broader market.
Expected return = Risk-free rate + Beta × (Market return − Risk-free rate)
The risk-free rate represents the theoretical return from an investment with minimal default risk. The difference between market return and the risk-free rate is the market risk premium.
Beta measures how sensitive an investment has historically been to market movements:
- Beta of 1: sensitivity broadly equal to the market
- Beta above 1: greater sensitivity than the market
- Beta below 1: lower sensitivity than the market
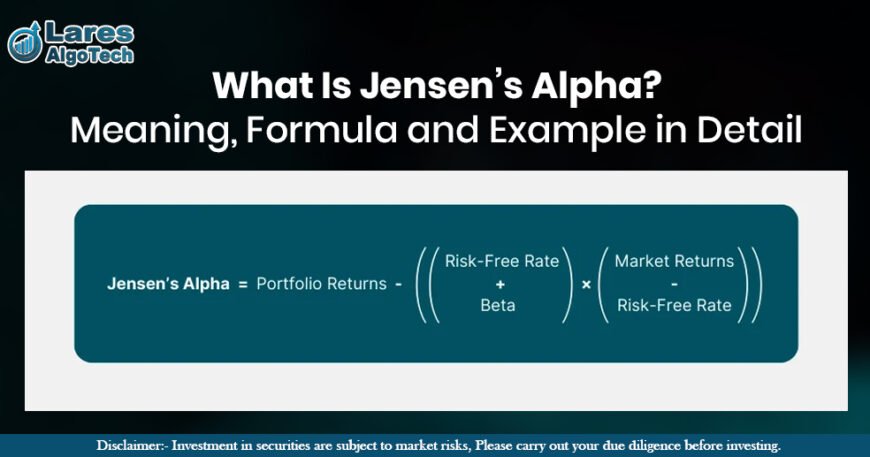
Jensen’s Alpha Formula
The formula is:
Jensen’s Alpha (α) = Rp − [Rf + βp(Rm − Rf)]
Where:
- α = Jensen’s Alpha
- Rp = actual portfolio return
- Rf = risk-free rate
- βp = portfolio beta
- Rm = market or benchmark return
- Rm − Rf = market risk premium
The figure inside the brackets is the CAPM-predicted return. Alpha is the portion left after subtracting that expectation. All inputs must cover the same period.
Jensen’s Alpha Calculation: Detailed Example
Assume the following annual data for a hypothetical equity portfolio:
- Actual portfolio return: 15%
- Risk-free rate: 5%
- Portfolio beta: 1.20
- Market return: 11%
Step 1: Find the market risk premium.
Market risk premium = 11% − 5% = 6%
Step 2: Adjust it for beta.
Beta-adjusted premium = 1.20 × 6% = 7.20%
The portfolio’s beta is above 1, so CAPM requires a higher return than it would for a portfolio with market-level beta.
Step 3: Calculate the expected return.
CAPM-expected return = 5% + 7.20% = 12.20%
Step 4: Calculate Jensen’s Alpha
Jensen’s Alpha = 15% − 12.20% = 2.80%
The portfolio’s Jensen’s Alpha is +2.80%. It outperformed its CAPM-implied return by 2.8 percentage points during the period. This does not mean it is guaranteed to outperform by that amount in future or prove that the result came entirely from manager skill.
How to Interpret Jensen’s Alpha
Positive Alpha
A positive value means the investment earned more than the CAPM-predicted return for its beta. It may indicate effective portfolio decisions, favourable security selection or exposure to factors the model does not capture. Investors should examine whether the result remains positive across different periods and after costs.
Zero Alpha
An alpha close to zero means actual performance was broadly consistent with the CAPM expectation. The portfolio delivered approximately the return predicted for its measured market risk.
Negative Alpha
A negative value means performance fell below the CAPM estimate. Possible reasons include weak investment decisions, expenses, unsuitable positioning or risks not adequately represented by beta.
Why Is Jensen’s Alpha Useful?
Jensen’s Alpha can help investors:
Evaluate risk-adjusted performance: It distinguishes raw return from performance relative to market risk.
Compare similar portfolios: It supports comparisons between investments with comparable mandates and benchmarks.
Assess portfolio management: Persistent positive alpha may justify closer study of a manager’s process, although it is not conclusive evidence of skill.
Add context: It avoids assuming every portfolio carries the same market exposure.
Jensen’s Alpha vs. Sharpe Ratio
Both measures evaluate risk-adjusted performance, but they define risk differently.
- Jensen’s Alpha uses beta and measures performance against a CAPM-implied return.
- Sharpe Ratio uses standard deviation and evaluates excess return relative to total volatility.
Jensen’s alpha can suit a diversified portfolio assessed against a relevant benchmark. The Sharpe Ratio may be more informative when total volatility matters. Neither should be used alone.
Limitations of Jensen’s Alpha
Dependence on CAPM
CAPM is simplified. Returns may be influenced by size, value, momentum, liquidity and other factors a single beta does not capture.
Historical beta
Beta depends on the period, data frequency and market conditions used to estimate it. Past sensitivity may not represent future behaviour.
Benchmark selection
An unsuitable benchmark can produce misleading alpha. The index should reflect the portfolio’s investment universe and strategy.
Risk-free rate and time period
The selected rate should match the investment’s currency and measurement period. Inconsistent inputs can distort the calculation.
Fees and expenses
Investors should check whether returns are shown before or after expenses. A positive gross alpha may shrink or turn negative after fees and transaction costs.
Lack of persistence
Positive historical alpha can result from chance, temporary factor exposure or favourable conditions. It does not ensure future outperformance.
Best Practices for Using Jensen’s Alpha
Use an appropriate benchmark, keep return periods consistent and analyse alpha across multiple periods. Confirm whether returns are gross or net of costs. Combine alpha with measures such as the Sharpe Ratio, standard deviation and maximum drawdown, plus qualitative factors including process and risk controls.
Conclusion
Jensen’s Alpha shows how much an investment’s actual return exceeded or fell short of the CAPM-predicted return for its beta. A positive value indicates outperformance relative to the model, zero indicates performance broadly in line with expectations, and a negative value indicates underperformance.
The metric offers useful risk-adjusted context, but its output depends on beta, benchmark choice, risk-free rate, fees and the analysis period. Investors should therefore treat Jensen’s Alpha as an analytical tool—not a prediction, guarantee or standalone basis for an investment decision.
Frequently Asked Questions
Can Jensen’s Alpha be negative when an investment makes a profit?
Yes. An investment can earn a positive return but have negative alpha when it earns less than CAPM predicts for its beta.
Does positive alpha prove manager skill?
No. It may also arise from chance, benchmark mismatch or risk factors omitted by CAPM.