Introduction
An Indian manufacturer has regular orders and reliable customers and plans to open another production unit. However, it needs additional capital and better technology to expand. An overseas company recognizes the opportunity and agrees to invest in exchange for an ownership stake.
This is one way foreign direct investment, commonly called FDI, works.
The Indian business may receive funding, technical knowledge, and access to international customers. The overseas investor receives ownership and an opportunity to benefit from the company’s future growth.
However, an FDI transaction involves more than transferring money. The parties must examine business eligibility, ownership limits, valuation, investment terms, and reporting requirements.
Understanding how foreign direct investment works in India becomes easier when we follow the money, examine the ownership arrangement, and connect the process with practical examples.
The examples in this article are hypothetical and simplified to explain the concepts.
What Is Foreign Direct Investment?
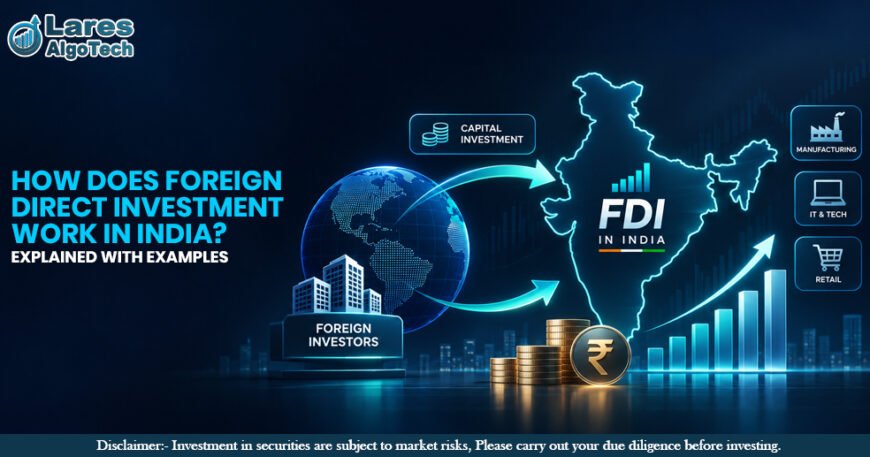
Foreign direct investment involves investment through eligible equity instruments by a person resident outside India in an Indian company.
Under RBI’s framework, FDI includes investment in an unlisted Indian company or investment representing 10% or more of a listed Indian company’s post-issue paid-up equity capital on a fully diluted basis.
“Fully diluted” means considering the shares that would exist if all possible sources of conversion were exercised.
An important distinction is that the 10% threshold applies to the listed-company definition. It should not be treated as a universal minimum for investment in unlisted Indian companies.
In everyday business terms, the foreign investor acquires an ownership interest in the company.
For example, an overseas investor may subscribe to shares representing 20% of an unlisted Indian software company. The company receives capital, and the investor becomes one of its shareholders.
This differs from a foreign customer paying the company for software services. A customer purchases a service, while an equity investor acquires a stake in the business.
Why Do Foreign Investors Invest in India?
Foreign investors usually evaluate several commercial opportunities before investing.
Some want access to Indian customers. Establishing local operations can help them understand purchasing preferences, adapt products, and improve customer support.
Others are interested in manufacturing capabilities, skilled employees, local suppliers, or opportunities to export from India.
For example, an overseas engineering company might invest in an Indian component manufacturer because the business has suitable production facilities and established customer relationships.
Indian companies also have different reasons for seeking foreign investment. They may need capital for expansion, product development, machinery, or acquisitions.
Sometimes, the investor’s experience is as valuable as the money. A foreign partner might help improve production processes, introduce stronger financial controls, or connect the business with overseas distributors.
The partnership works best when both sides understand what they expect from it. Funding alone cannot resolve weak demand, poor management, or disagreements about business priorities.
How Does FDI Work in India? A Step-by-Step Explanation
Although transactions differ, the investment process generally follows several connected stages.
Identify the Business Opportunity
The overseas investor first decides what it wants to achieve.
It may establish a new Indian subsidiary, invest in an existing company, form a joint venture, or purchase shares from current shareholders.
Each option has different implications.
Starting a new operation involves building facilities, hiring employees, and developing customer relationships. Investing in an existing company provides access to its operating business, along with its liabilities and commercial risks.
The Indian company should also identify its objective. Does it need fresh funding, technical expertise, international market access, or an opportunity for existing shareholders to sell?
Clear objectives help the parties choose a suitable investment structure.
Check the Applicable Investment Rules
Before finalizing commercial terms, the parties must examine whether the proposed investment is permitted.
This assessment includes the company’s actual activities, foreign ownership limits, entry route, and investor eligibility.
A broad description such as “technology business” may be insufficient. A company developing software can raise different regulatory questions from a company providing regulated financial services.
The investor’s ownership structure also matters. The parties may need to establish who ultimately owns or controls the overseas investing entity.
Addressing these questions early can prevent delays after negotiations have progressed.
Conduct Due Diligence
Due diligence helps the investor understand the business it plans to invest in.
The review commonly covers:
- Financial statements and borrowings.
- Customer and supplier contracts.
- Tax matters and outstanding liabilities.
- Business licenses and registrations.
- Intellectual property ownership.
- Employment arrangements and disputes.
Suppose a software company claims that its main product is its most valuable asset. The investor needs to examine whether the company owns the relevant software rights and whether employees or contractors properly assigned those rights.
Commercial issues deserve equal attention. Does the company depend heavily on one customer? Are its sales forecasts realistic? Can it operate effectively without the founder’s daily involvement?
The Indian company should also assess the investor’s credibility, funding capacity, and expectations.
Agree on Valuation and Ownership
The parties negotiate how much the business is worth and what ownership the investor will receive.
Consider an Indian company with an agreed pre-investment valuation of ₹20 crore. An overseas investor contributes ₹5 crore through newly issued ordinary shares.
In a simplified transaction, the calculation would be:
| Particulars | Amount |
| Pre-investment valuation | ₹20 crore |
| New investment | ₹5 crore |
| Post-investment valuation | ₹25 crore |
| Investor’s ownership after investment | 20% |
| Existing shareholders’ combined ownership | 80% |
The investor’s stake is calculated by dividing ₹5 crore by the ₹25 crore post-investment valuation.
The negotiated price must also meet applicable pricing requirements. Agreement between the parties does not, by itself, establish regulatory compliance.
Negotiate Governance and Investment Documents
The ownership percentage is only one part of an investment arrangement.
The parties may also negotiate board representation, financial reporting, approval rights for major decisions, and provisions for future fundraising.
For example, an investor might want approval rights before the company takes substantial new debt or sells an important business division.
The founders may want sufficient freedom to manage recruitment, sales, and everyday operations.
Clear documents help establish how decisions will be made and how disagreements will be handled.
Complete Approvals and Transfer Funds
The parties obtain any required approvals and complete the agreed conditions before closing the transaction.
For a fresh share issue, the company receives the subscription money and issues shares to the investor.
For a purchase of existing shares, the selling shareholder receives the purchase consideration.
RBI’s payment regulations provide for permitted banking channels. For equity issuance under the relevant Schedule I framework, equity instruments generally need to be issued within 60 days of receiving consideration. Applicable refund requirements must be followed if issuance does not occur within that period.
Complete Reporting and Continuing Compliance
Receiving funds does not finish the process.
An Indian company issuing equity instruments classified as FDI generally needs to report the issue through Form FC-GPR within 30 days of issuing those instruments.
Share transfers can involve different reporting requirements. Annual reporting of foreign liabilities and assets may also apply.
A practical closing checklist should therefore cover both the transaction and the obligations that continue afterwards.
Automatic Route vs Government Route
India has two main entry routes for foreign direct investment.
Automatic Route
Under the automatic route, the foreign investment does not require prior approval from the RBI or the Central Government, provided the applicable requirements are satisfied.
However, “automatic” does not mean unrestricted.
The investment must still comply with relevant ownership limits, eligibility requirements, sectoral conditions, and reporting obligations.
The company may also need operational licenses or approvals under other laws.
Government Route
Under the government route, prior government approval is required.
The investment must comply with applicable rules and the conditions attached to the approval.
| Point of comparison | Automatic route | Government route |
| Prior FDI approval | Not required where applicable conditions are met | Required |
| Main assessment | Eligibility, limits, and applicable conditions | Eligibility, limits, applicable conditions, and approval terms |
| Reporting | Applicable reporting continues. | Applicable reporting continues. |
| Other business requirements | Remain relevant | Remain relevant |
India permits up to 100% FDI through the automatic route in most sectors. Nevertheless, the proposed business activity and investment structure must be checked individually.
Types of Foreign Direct Investment
FDI can be classified according to the business relationship and how the investment is established.
Horizontal FDI
Horizontal FDI occurs when a business invests abroad in the same or a similar activity.
For example, an overseas furniture manufacturer invests in an Indian furniture manufacturing company.
The objective might be to serve local customers, increase production capacity or establish a regional business presence.
Vertical FDI
Vertical FDI involves investment in another stage of the supply chain.
An overseas automobile manufacturer investing in an Indian component producer is an example of backward integration. The investment connects the manufacturer more closely with its supply base.
Investment in distribution or sales operations can represent forward integration.
Conglomerate FDI
Conglomerate FDI involves investment in an unrelated business.
For instance, an overseas consumer goods company might invest in an Indian hospitality business as part of a diversification strategy.
Such investments require careful assessment because experience in one industry may not transfer easily to another.
Greenfield Investment
A greenfield investment establishes a new operation.
For example, a foreign manufacturer may fund a newly incorporated Indian subsidiary that builds a factory, recruits employees and starts production.
This approach allows the investor to develop operations around its requirements, but establishing the business can take time.
Brownfield Investment
A brownfield investment involves an existing business or operation.
Acquiring an established manufacturing company is one example. The investor gains access to existing facilities, employees and customers, while also needing to assess their condition and suitability.
These classifications can overlap. A new Indian factory producing the same products as its foreign parent can be both greenfield and horizontal.
Practical Examples of FDI in India
Following where the money goes makes the differences between investment structures clearer.
Example 1: Funding an Indian Software Company
An unlisted Indian software company wants to expand its product team and enter additional markets.
An overseas investor contributes ₹5 crore for newly issued shares representing 20% of the company after investment.
The company receives the ₹5 crore and can use it for its business requirements, subject to the agreed terms and applicable rules.
Existing shareholders retain their shares, but their percentage ownership falls because additional shares have been issued.
The funding supports expansion. Whether that expansion succeeds depends on product quality, customer demand and execution.
Example 2: Establishing a Manufacturing Subsidiary
An overseas equipment manufacturer establishes an eligible Indian subsidiary and contributes equity capital.
The subsidiary uses its resources to lease premises, purchase machinery and recruit employees.
The parent company may contribute technical knowledge and supplier relationships alongside funding.
This investment creates a new operating business. However, production delays, recruitment difficulties and weaker-than-expected demand can still affect its performance.
Example 3: Buying Shares from an Indian Founder
An overseas investor purchases a 25% stake directly from an Indian founder for ₹10 crore.
The ₹10 crore goes to the founder selling the shares.
The company’s bank balance does not automatically increase because it has not issued new shares.
This distinction matters when reading investment announcements. A transaction may involve fresh funding, a shareholder sale or a combination of both.
Understanding FDI Policy in India
India’s FDI framework combines policy, foreign exchange rules and sector-specific requirements.
DPIIT formulates FDI policy. FEMA, the Non-Debt Instruments Rules and RBI directions provide important parts of the legal and operational framework.
Companies must also examine laws and requirements relevant to their particular activities.
A useful assessment starts with five questions:
Is the activity open to foreign investment?
What ownership limit applies?
Which entry route applies?
Are there investor-specific restrictions?
What approvals, conditions and reporting obligations apply?
The Consolidated FDI Policy should be read alongside subsequent amendments.
Investor ownership is one area where older explanations can become misleading. Changes implemented in 2026 allow certain investor entities with non-controlling beneficial ownership of up to 10% from countries sharing a land border with India to use the automatic route, subject to applicable sectoral requirements, other conditions and specified reporting.
This is a conditional relaxation. It should not be interpreted as unrestricted permission for every investment connected with those countries.
Benefits of FDI for Indian Businesses and the Economy
Capital for Business Expansion
Fresh equity can help a company increase capacity, develop products or enter additional locations.
However, a purchase of existing shares does not provide the same direct funding benefit unless the transaction also includes fresh capital.
Technology and Operating Experience
An experienced investor may introduce production methods, quality controls or management systems.
For example, a manufacturer could improve product consistency by adopting better inspection procedures.
The benefit depends on whether knowledge is transferred and effectively used.
Access to Overseas Customers
A foreign partner may introduce the Indian business to distributors or customers in other countries.
This can make international expansion easier, although the company still needs suitable products, dependable delivery and competitive pricing.
Employment and Supplier Opportunities
Expanding operations may create jobs and demand for local logistics, services and components.
The scale of these benefits varies. A new factory and an acquisition of an existing company can have different immediate effects on employment.
Risks and Challenges of FDI
Ownership Dilution and Disagreements
Founders receiving fresh equity give up a portion of their percentage ownership.
Disputes can arise over expansion, expenditure, dividends or recruitment. A founder might favour rapid growth while the investor wants to preserve cash.
Integration Difficulties
Different management practices, reporting systems and workplace cultures can make cooperation difficult.
Legal documents establish rights, but effective working relationships require communication and realistic expectations.
Currency Risk
An overseas investor evaluates returns in its own currency.
A business can increase in rupee value while delivering a smaller foreign currency return if exchange rates move unfavourably.
Business and Exit Risk
FDI remains exposed to competition, financial losses and changes in customer demand.
Selling an unlisted stake can also take time. A suitable buyer may be unavailable, or the parties may disagree about valuation.
An expected return is therefore different from an assured outcome.
FDI vs FPI: What Is the Difference?
Foreign portfolio investment is commonly associated with investment in listed securities. FDI includes equity investment in unlisted Indian companies and qualifying holdings in listed companies.
For listed-company equity, RBI’s definitions generally distinguish FPI holdings below 10% from FDI holdings of 10% or more on the relevant fully diluted basis.
An existing FDI holding that subsequently falls below 10% continues to be treated as FDI under the stated rule.
| Aspect | FDI | FPI |
| Typical purpose | Business participation or strategic exposure | Portfolio allocation and investment returns |
| Common setting | Unlisted investment or qualifying listed holding | Listed securities investment |
| Management involvement | May involve negotiated governance rights | Usually less operational involvement |
Holding period alone does not determine the classification. A portfolio investor can hold securities for many years.
Frequently Asked Questions
Can a foreign investor own 100% of an Indian company?
Yes, where the activity, investor eligibility and applicable requirements permit it. Exceptions and conditions must be assessed individually.
Does FDI always give the investor control?
No. A minority investment may provide limited influence. Decision-making rights depend on ownership, agreements and applicable law.
Does every FDI transaction bring fresh money into the company?
No. Fresh share subscriptions fund the company. Purchases from existing shareholders pay the sellers.
How do foreign investors earn returns?
Possible returns include dividends and gains from selling shares. Both depend on business performance and applicable requirements. Sale proceeds from eligible repatriable investments can generally be remitted overseas net of applicable taxes under the relevant rules.
What should an Indian company assess before accepting FDI?
It should assess funding needs, investor credibility, valuation, ownership dilution, governance rights and future expectations.
Foreign direct investment works best when the commercial arrangement and compliance process support each other. For an Indian business considering overseas capital, the starting point is understanding who receives the money, what rights the investor gains and how both parties expect the business to develop.